Showing posts with label online stock trading and investments. Show all posts

Wednesday, November 17, 2010

personal finances help


The Asian Development Bank has roped in the European Investment Bank to invest in large-scale solar power plants in India. The ADB is committed to arrange finances for India’s ambitious National Solar Mission projects.


The Asian Development Bank has been working closely with many Asian countries to provide them financial, technical and policy-related support for expanding solar energy infrastructure. The ADB is playing an active role in India to make solar energy more popular. In addition to the European Investment Bank, the ADB has also attracted funding from the US Import-Export Bank and Germany’s KWF.


Under the National Solar Mission, India plans to install 20,000 MW solar-based power generation capacity by 2022. The current install capacity is a dismal 14 MW. The 20,000 MW capacity also includes the off-grid rural power plants. In order to rapidly increase the installed capacity the Indian government has announced two massive solar farm projects, one each in Rajasthan and Gujarat.


Both these states are blessed with substantially high solar radiation resource and also have large areas of unused lands due to lower agricultural land use. Rajasthan has the vast Thar desert while Gujarat has vast wastelands in the west. Gujarat has set aside 2,500 hectare for a 1,000 MW plant while Rajasthan has set aside 8,000 hectare for a 3,000 MW plant. Construction of these plants is expected to start after 2013, that is, during the second phase of the National Solar Mission.


The ADB is also supporting the project developers who intend to set up power plants during the first phase. The first phase aims at installing 1,1o0 MW by 2013; ADB will support 350 MW of these installations. The smaller power plants have been provided with 50 percent loan guarantees and project developers will also provided direct loans.


The Asian Development Bank has been working closely with several ministries of the Indian government to devise overall policies and logistical support mechanism in order to make the solar energy projects commercially viable. The bank would also provide capital grants to cover up the difference between the cost of solar power generation and the average cost of generation from conventional sources.


Such collaborations with international funding agencies help in bridging the financial gap that exists for any new renewable energy technologies. In the absence of a clear agreement on international funding as part of an international climate change treaty, such partnerships with European and American banks helps in the quick implementation of these clean technology projects in the developing countries.


Image: technicolorcavalry/Flickr/CC


The views presented in the above article are author’s personal views and do not represent those of TERI/TERI University where the author is currently pursuing a Master’s degree.


Follow Mridul Chadha on Twitter and Facebook

Consumers bewildered by a rash of resetting rates on loans and various outstanding credit lines now have the same tools banks have to aggregate all their debt in one place, after free online personal finance tool Credit Sesame launched a beta version today to help users get a complete financial snapshot all in one place.


Previously only available to banks or brokers, Credit Sesame uses an in-house loan analytics engine to help users instantly view their credit and debt in one place, while monitoring and tracking often baffling financial information like their credit score, home value and debt-to-income ratio simultaneously.


The news that they can now take their finances fully into their own hands is part of a continuing trend of consumers sick of commercial banks pushing their own complementary loan products on them — or who may just be sick of their bank or broker all together.


Under the company’s system, users are first asked to register their portfolios using the same security technology and encryption methods as banks and financial institutions use, and then Credit Sesame automatically retrieves users’ relevant data like debt, credit, and mortgages so that they don’t have to enter their information manually.


They can then fiddle with Credit Sesame’s tools to set personal goal parameters; see and apply for a wide variety of loans that may fit their restructuring needs; and even create a “what if” scenario that allows them to view multiple scenarios for potential savings or loans based on changes to a user’s financial situation such as a divorce or a job loss.


By using complex algorithms and portfolio “depth” testing, the new beta site will now create 5,000 scenarios with thousands of lending products to help each user find the three best pre-qualified solutions—saving an average user hundreds of dollars a month as they streamline their finances via the web ecosphere.


“We find homeowners as much as $600 a month in savings through restructuring, refinancing and new pre-qualified low-interest loan offers,” said Adrian Nazari, CEO and founder of Credit Sesame. “That’s $7,200 of yearly savings. If that money was put toward debt repayment, imagine how much faster that loan would be paid off and how much money would be saved. The opportunities are out there.”


Since launching to private testers in September, Credit Sesame currently manages $250 million in loans and has generated more than $18 million in lifetime savings for its users.


Once registered, the site will continue delivering a free monthly credit score and instant alerts when more optimal savings opportunities become available.


Next Story: Hulu Plus officially launches at $7.99 a month, now on Roku boxes Previous Story: The many definitions of a VC’s no – Part Two


alpine payment systems scam

Scripting <b>News</b>: Design challenge: River of <b>News</b> in HTML

Design challenge: River of News in HTML. By Dave Winer on Tuesday, November 16, 2010 at 8:13 PM. I'm a big believer in designers, programmers, writers, artists, news people all working together. Permanent link to this item in the ...

Was Tony Parker Cheating? Mystery Teammate&#39;s Wife Revealed... Erin <b>...</b>

The father of San Antonio Spurs star Brent Barry -- whose wife Erin is reportedly the other woman in a Tony Parker love triangle -- tells TMZ he's worried that Brent will be "devastated" by the news. Tony Parker Cheating With Brent ...

Lujiazui Breakfast: <b>News</b> And Views About China Stocks (Nov. 18 <b>...</b>

Investors and traders in China's main financial district are talking about the following before the start of trade today: Shanghai's main stock index fell 1.9% yesterday amid concerns about the impact of government efforts to slow down ...


12th Annual Charity Golf Tournament benefitting the Eureka Camp Society-Apex Secondary School-presented by SNC LAVALIN Pacific Liaicon and Associates Benefitting the Eureka Camp Society-Apex Secondary School photos by Ron Sombilon Gallery (367) by Ron Sombilon Gallery


Scripting <b>News</b>: Design challenge: River of <b>News</b> in HTML

Design challenge: River of News in HTML. By Dave Winer on Tuesday, November 16, 2010 at 8:13 PM. I'm a big believer in designers, programmers, writers, artists, news people all working together. Permanent link to this item in the ...

Was Tony Parker Cheating? Mystery Teammate&#39;s Wife Revealed... Erin <b>...</b>

The father of San Antonio Spurs star Brent Barry -- whose wife Erin is reportedly the other woman in a Tony Parker love triangle -- tells TMZ he's worried that Brent will be "devastated" by the news. Tony Parker Cheating With Brent ...

Lujiazui Breakfast: <b>News</b> And Views About China Stocks (Nov. 18 <b>...</b>

Investors and traders in China's main financial district are talking about the following before the start of trade today: Shanghai's main stock index fell 1.9% yesterday amid concerns about the impact of government efforts to slow down ...


alpine payment systems scam

Scripting <b>News</b>: Design challenge: River of <b>News</b> in HTML

Design challenge: River of News in HTML. By Dave Winer on Tuesday, November 16, 2010 at 8:13 PM. I'm a big believer in designers, programmers, writers, artists, news people all working together. Permanent link to this item in the ...

Was Tony Parker Cheating? Mystery Teammate&#39;s Wife Revealed... Erin <b>...</b>

The father of San Antonio Spurs star Brent Barry -- whose wife Erin is reportedly the other woman in a Tony Parker love triangle -- tells TMZ he's worried that Brent will be "devastated" by the news. Tony Parker Cheating With Brent ...

Lujiazui Breakfast: <b>News</b> And Views About China Stocks (Nov. 18 <b>...</b>

Investors and traders in China's main financial district are talking about the following before the start of trade today: Shanghai's main stock index fell 1.9% yesterday amid concerns about the impact of government efforts to slow down ...

Friday, September 24, 2010

personal financeonline personal finance


ywqgzmkvicvnth

After Months of Speculation, Anisette Brasserie Bids Au Revoir <b>...</b>

Unfortunately, we called it. In an additional bout of shutter news, months and months after rumors swirled that Alain Giraud's Anisette Brasserie was about to call it quits, his...

Ngmoco releases We City | iLounge <b>News</b>

iLounge news discussing the Ngmoco releases We City. Find more Apps + Games news from leading independent iPod, iPhone, and iPad site.

Can &#39;Fox <b>News</b> North&#39; win its next battle? - Canada - Macleans.ca

Sun TV's Canadian-content promise might be its best selling feature.


After Months of Speculation, Anisette Brasserie Bids Au Revoir <b>...</b>

Unfortunately, we called it. In an additional bout of shutter news, months and months after rumors swirled that Alain Giraud's Anisette Brasserie was about to call it quits, his...

Ngmoco releases We City | iLounge <b>News</b>

iLounge news discussing the Ngmoco releases We City. Find more Apps + Games news from leading independent iPod, iPhone, and iPad site.

Can &#39;Fox <b>News</b> North&#39; win its next battle? - Canada - Macleans.ca

Sun TV's Canadian-content promise might be its best selling feature.


big white booty

After Months of Speculation, Anisette Brasserie Bids Au Revoir <b>...</b>

Unfortunately, we called it. In an additional bout of shutter news, months and months after rumors swirled that Alain Giraud's Anisette Brasserie was about to call it quits, his...

Ngmoco releases We City | iLounge <b>News</b>

iLounge news discussing the Ngmoco releases We City. Find more Apps + Games news from leading independent iPod, iPhone, and iPad site.

Can &#39;Fox <b>News</b> North&#39; win its next battle? - Canada - Macleans.ca

Sun TV's Canadian-content promise might be its best selling feature.


personal finance manager


Washington (CNN) - Fresh on the heels of Joe Miller's surprising win over Sen. Lisa Murkowski in the Alaska Republican Senate primary, the Tea Party movement is setting its sights on Delaware.


Now the Delaware Republican Party is taking heed – and taking on – the Tea Party-backed candidate in the state's Republican Senate primary, sparking a war of words between the state's establishment GOP and the Tea Party movement.


It's a race that pits conservative Tea Party favorite Christine O'Donnell against moderate Rep. Mike Castle, Delaware's former two-term governor and lone Congressman since 1993.


Both candidates' campaigns have become increasingly caustic, especially as Tea Party-backed candidates across the country have picked up win after win against GOP establishment candidates.


The Tea Party Express endorsed the conservative O'Donnell in July, and recently committed to spending at least six-figures in the state.


"We are launching an aggressive multimedia and multi-platform campaign to help propel Christine O'Donnell to victory, and we've only just begun," Amy Kremer, Chairman of the Tea Party Express, said in a statement.


The group originally planned to spend about $250,000 on the race, but is now considering expanding their presence with TV and radio ad buys in Philadelphia, said Tea Party Express political director Joe Wierzbicki.


A similar last minute media blitz by the Tea Party Express is credited with propelling Miller – a formerly little known candidate – to victory over Murkowski, the Republican Party-backed incumbent.


The group launched a series of TV and radio ads Thursday that support O'Donnell, and rail against Castle as a liberal candidate who "just keeps supporting the failed policies of Nancy Pelosi and Harry Reid."


It's a move that has the Castle campaign fighting back.


"Out-of-state interest groups have threatened to spend half a million dollars to fund the disgusting tactics being used by the O'Donnell campaign to make accusations," said Castle campaign manager Mike Quaranta.


Meanwhile, the Castle campaign has launched therealchristine.com, a site devoted to aggregating negative news about O'Donnell.


Tom Ross, state committee chairman of the Delaware Republican Party, defended the negative nature of the site. "The stories might not be flattering, but they are factual. ...Sometimes it is necessary to make sure that the facts get out there," Ross said.


O'Donnell has faced criticism over her personal finance issues and leftover debt from previous, unsuccessful bids for a Delaware Senate seat. She has also been accused of misstating the results of her run against Joe Biden.


When asked to clarify her remarks in an interview Thursday with radio host Dan Gaffney of WGMD, O'Donnell seemed to grow increasingly frustrated, and ultimately blamed her statements on a grueling campaign schedule.


Ross, who is backing Castle, said that O'Donnell's history is troubling.


"This is a group and candidate that clearly seem to have a problem with facts. It is shocking that they would come in and support a candidate of Christine O'Donnell's ilk," he said.


"It is sad that the group didn't investigate the candidate that they're supporting… and surprising they would take their supporters' money that they donated and squander it in such a fashion," Ross said.


Ross also questioned whether O'Donnell is capable of pulling off an upset similar to Miller's win in Alaska.


"In Alaska, it was that Joe Miller is an Ivy League grad, a war hero, excellent standing in the community," Ross said. "Look at Christine O'Donnell. She has none of those attributes. She is career politician. She's run unsuccessfully for Senate three times."


Yet, Wierzbicki criticized Ross for dismissing O'Donnell, calling her a true conservative.


" is everything that is wrong with the establishment of the Republican Party. He should be fired for serving to undermine a Republican candidate who stands on conservative principles. It's his job to advance all Republicans in the state of Delaware. Instead he has become a tool for those who wish to thwart the Republican Party platform and turn the GOP into a Democrat-lite outfit. We find him reprehensible and shameless," Wierzbicki said.


Republican Gov. Chris Christie of neighboring New Jersey endorsed Castle Thursday.


The winner will face Democrat Chris Coons in the race for Vice President Joe Biden's former seat.


If you walked into the average bookstore, you'd think that women rule the roost when it comes to personal finance. From Suze Orman's now-classic Women and Money to the more recent (and more colorfully titled) Bitches on a Budget, there's no shortage of do-it-yourself financial advice tailored to women.


Apparently, though, when women make the momentous move from self-help to seeking professional advice about investing and retirement, things go rapidly downhill. A recent study by the Boston Consulting Group revealed that women perceived themselves as receiving wealth management services at a level of quality that is inferior to that received by their male counterparts.


According to the study, women are the key decision-makers when it comes to 27% of the wealth worldwide: that's $20 trillion! But despite the massive chunk of power they wield, 55% of the women surveyed in the study said they felt their wealth manager could do a better job of advising them. Almost a quarter of the respondents said private banks needed "significant improvement" in the services they offer to women.


"The dissatisfaction stems from the unshakable perception that men get more attention, better advice, and sometimes even better terms and deals," according to study co-author Peter Damisch. "We heard this sense of subordination time and time again in our interviews."


This perceived disparity in service arose from several key disconnects in the relationships and communications between women and their financial advisers. Manisha Thakor, Chartered Financial Analyst and women's financial literacy advocate, offers some steps savvy female investors can take to avoid being under-served by their wealth managers and investment advisers:


1. Find your adviser and get your financial education from women-run resources.


The financial services industry is dominated by males and therefore the "DNA is structured around the male experience," Thakor explains, adding that she sees many firms making an effort to change this. Most financial advisers are men, who may not inherently understand the whole-life nature of the average woman's financial plans and needs. They also may have very different communication styles than their women clients.


Thakor recommends women use women-created resources like LearnVest and DailyWorth to educate themselves in order to avoid the intimidation factor when talking about investment products with their advisers. She also encourages women to consult Garrett Planning Network, founded by Certified Financial Planner Sheryl Garrett, to locate a local certified financial planner who works on an hourly-fee-only basis. Taking these steps, Thakor explains, may alleviate the concern expressed by many women in the BCG study that they were not being taken seriously or talked to on the same level as male clients by their financial advisers.


2. Expressly state your ideal career trajectory, then ask how you should alter your investment plans accordingly.


In the BCG study, women stated that their investment advisers fundamentally misunderstood what was actually important to them, and recommended a too-narrow range of inappropriate investment vehicles as a result. Many said their advisers assumed they had a lower risk tolerance than they actually did, or that their advisers focused on short-term results and disregarded their long-term goals, which often included time out to care for a child or parent.


Thakor offers women a script of sorts to remedy this communication disconnect. "Go in and say: "I want to be a mom and I may take X amount of time out of the work force," she advises. Then ask, "How do we adjust how much I need to save and how I should invest to compensate for this?"


3. Start saving early.


big white booty info

Small Business <b>News</b>: An Owner&#39;s Manual

If only there were an owner's manual that came with your small business telling you what works, what doesn't and what are the best ways to move ahead in your.

Understanding the Forbes redesign « Talking Biz <b>News</b>

Dvorkin had founded True/Slant, an online news network. Previously, he had been executive editor at Forbes magazine, where he spearheaded an earlier redesign, managed the annual Forbes 400 Richest Americans list and created the ...

Actual Real Life Good Internet <b>News</b>: Super Wi-Fi Coming Soon <b>...</b>

Most of the time, news about the internet is both hard to understand and seemingly bad. There are always stories coming out about net neutrality where you.


Small Business <b>News</b>: An Owner&#39;s Manual

If only there were an owner's manual that came with your small business telling you what works, what doesn't and what are the best ways to move ahead in your.

Understanding the Forbes redesign « Talking Biz <b>News</b>

Dvorkin had founded True/Slant, an online news network. Previously, he had been executive editor at Forbes magazine, where he spearheaded an earlier redesign, managed the annual Forbes 400 Richest Americans list and created the ...

Actual Real Life Good Internet <b>News</b>: Super Wi-Fi Coming Soon <b>...</b>

Most of the time, news about the internet is both hard to understand and seemingly bad. There are always stories coming out about net neutrality where you.


big white booty

Small Business <b>News</b>: An Owner&#39;s Manual

If only there were an owner's manual that came with your small business telling you what works, what doesn't and what are the best ways to move ahead in your.

Understanding the Forbes redesign « Talking Biz <b>News</b>

Dvorkin had founded True/Slant, an online news network. Previously, he had been executive editor at Forbes magazine, where he spearheaded an earlier redesign, managed the annual Forbes 400 Richest Americans list and created the ...

Actual Real Life Good Internet <b>News</b>: Super Wi-Fi Coming Soon <b>...</b>

Most of the time, news about the internet is both hard to understand and seemingly bad. There are always stories coming out about net neutrality where you.


Chrysler Building Third Avenue by Emilio Guerra


Chrysler Building Third Avenue by Emilio Guerra


Saturday, September 18, 2010

managing your personal finances


Are you a fan of the GTD personal productivity system? Well if you like "Getting Things Done," here's GFD, Getting Finances Done, which shows you how to map David Allen's same principals to managing your personal finance and achieving your financial goals.


Applying GTD principles to your personal finances - Part 1 [Getting Finances Done]


Are you a fan of the GTD personal productivity system? Well if you like "Getting Things Done," here's GFD, Getting Finances Done, which shows you how to map David Allen's same principals to managing your personal finance and achieving your financial goals.


Applying GTD principles to your personal finances - Part 1 [Getting Finances Done]


eric seiger do how to lose weight fast penis extender

<b>News</b> - Lindsay Lohan: Failed Drug Test Report Is &quot;Nuts <b>...</b>

After it's reported that she flunked a drug test and could go back to jail, she tells Us, "I'm fine"

Sarah Palin Calls On Fox <b>News</b> To Help Republicans Campaign For <b>...</b>

In a speech at the Iowa Republican Party's Reagan Dinner fundraiser on Friday, former Alaska governor Sarah Palin called on the GOP to come together and support the party's nominees in November.

Baltimore Crime: Saturday crime <b>news</b>

Saturday crime news. State Senator Ulysses Currie pleaded not guilty to federal corruption charges. Triple stabbing on an MTA bus in West Baltimore. posted by ppatin at 11:07 AM ...


G20 Summit, London, G20 London, G20 Protests, G20 Demonstrations by G20London2009


Tuesday, September 14, 2010

personal finance and budgeting


  • Average gas prices--September 13, 2010


  • You voted: letter grades edge ahead in fuel economy poll


  • For rent: 4.5 billion-year-old ball of fire


  • What Obama's transportation proposals mean for travelers


  • TomTom provides update for XL 350, XXL 550, and XL 335 GPS devices


  • Cash for appliances: Rebates aplenty in states big and small


  • Apple curtails its free case program for the iPhone 4


  • Daily Dispatch: Death of the RSS reader?; Toronto produces entertaining video to promote e-waste recycling


  • September could be Home Star’s month—or not


  • LG's 60PX950, the first THX 3D plasma, headed to the CR Test labs!


Use Prepaid Travel Cards to Budget Travel Expenses


Vacation is a time to let loose and have a little fun. It's all too easy, however, to let having a little fun turn into spending way too much. Use prepaid travel cards to keep spending contained, secure, and in budget.

Photo by eliazar.


Finance and frugality blog WiseBread shares a set of tips on using prepaid travel cards for safe, secure, and budget-friendly travel spending.


A prepaid travel card is generally usable in the place of a debit or credit card. You can withdraw cash at an ATM, pay for purchases, and make travel reservations. And as the name suggests, you prepay these expenses by loading money onto the card.


It is just as secure as a debit or credit card, since the prepaid travel card is protected by a PIN and/or signature. In fact, some would say that prepaid travel cards are even more secure, since the money is not linked to your bank account and has a limited balance (which limits your exposure).


It can also be a handy tool for budgeting, since you would load only the money you plan on spending for the trip onto the card, which helps you stick to your travel budget.


Check out the full article at the link below for additional tips and tricks including what to look for when shopping for a card like avoiding cards with a cash-out fee. Have your own tips for keeping your money secure and sticking to a budget while traveling? Let's hear about it in the comments.


penis extender

Social networks as a source of daily <b>news</b> - Lost Remote

A new study by the Pew Research Center says that Americans are consuming more news than ever, with continued growth online — 34% said they went online for their news yesterday. When you add mobile, email and social networks to the ...

Good <b>News</b>: People Are Consuming More <b>News</b> «

The woes of the traditional media industry have fuelled concerns that traditional offline news sources are being replaced by online sources. But a new study by the Pew Center has found that online news consumption has actually increased ...

Small Business <b>News</b>: Facebook Phenomenon

The Facebook phenomenon may be the most important to small businesses on the Web currently, even if other tools like Twitter are sometimes more talked about.


Quizzle: Your Home, Money, Credit and LIfe - All in One Spot by QuizzleTown


internet marketing course

Social networks as a source of daily <b>news</b> - Lost Remote

A new study by the Pew Research Center says that Americans are consuming more news than ever, with continued growth online — 34% said they went online for their news yesterday. When you add mobile, email and social networks to the ...

Good <b>News</b>: People Are Consuming More <b>News</b> «

The woes of the traditional media industry have fuelled concerns that traditional offline news sources are being replaced by online sources. But a new study by the Pew Center has found that online news consumption has actually increased ...

Small Business <b>News</b>: Facebook Phenomenon

The Facebook phenomenon may be the most important to small businesses on the Web currently, even if other tools like Twitter are sometimes more talked about.


big white booty

Quizzle: Your Home, Money, Credit and LIfe - All in One Spot by QuizzleTown


Thursday, September 2, 2010

managing personal finances


  • Daily Dispatch: Navteq works to humanize GPS directions; Skyfire: flash capable iPhone browser submitted to Apple for approval


  • Q&A: Are liquid calcium supplements better?


  • Daily electronics deals


  • Labor Day deals without the legwork


  • Recycle your old rechargeable batteries


  • Apple revamped iPods, iTunes, and more


  • Bad eggs: 10 ways to cut your salmonella risk


  • New Whirlpool plant cooks up some jobs in Tennessee


  • Hurricane Earl: Keep yourself and your food safe


  • Should you buy an all-new car or a proven carry-over car?


  • Daily Dispatch: Navteq works to humanize GPS directions; Skyfire: flash capable iPhone browser submitted to Apple for approval


  • Q&A: Are liquid calcium supplements better?


  • Daily electronics deals


  • Labor Day deals without the legwork


  • Recycle your old rechargeable batteries


  • Apple revamped iPods, iTunes, and more


  • Bad eggs: 10 ways to cut your salmonella risk


  • New Whirlpool plant cooks up some jobs in Tennessee


  • Hurricane Earl: Keep yourself and your food safe


  • Should you buy an all-new car or a proven carry-over car?


photos of how to lose weight fast

Small Business <b>News</b>: Social Media Power!

If you haven't figured it out, gotten on board, jumped on the bandwagon (pick your own expression)...well, we're not going to try to talk you into it. Just be.

Coast Guard: Platform on fire in Gulf; 13 workers rescued – This <b>...</b>

An oil and gas production platform has exploded 102 miles off the central coast of Louisiana, with 13 people overboard, including one injured, the Coast Guard said Thursday morning. All 13 people have been accounted for, ...

Some Good <b>News</b> | Talking Points Memo

Over the weekend we brought you the news of the apparent arson attack at the construction site of the future Islamic Center of Murfreesboro, in Murfreesboro, Tennessee. The day after the incident, members of the congregation's board ...


MABUHAY ALLIANCE HOST THE 6TH ANNUAL ECONOMIC DEVELOPMENT CONFERENCE by mabuhayalliance


Wednesday, September 1, 2010

managing personal finances


gdgsylc

Rupert Murdoch and <b>News</b> Corp. to Be Swing Vote for 99-Cent iTunes <b>...</b>

The Los Angeles Times reports that Apple is still working to convince media companies to adopt its plan for 99-cent TV show rentals through its iTunes Store. According to those close to the negotiati.

Glenn Beck Launches The Blaze, <b>News</b> And Opinion Website

Glenn Beck is adding budding web mogul to his list of media titles. The radio and TV show host launched Monday a news and opinion website called The Blaze that he says will be "a place where you can find breaking news, ...

Fox <b>News</b> Remains Number Three Network On All Of Cable In August <b>...</b>

Fox News, like the rest of cable news, has seen year-to-year ratings declines this summer, and August was no exception. But when compared to the rest of cable, FNC remains the #3 network in total viewers (prime time).


Wednesday, August 25, 2010

personal finance books


A look at great reads from the editor of the TLS. This week: an economist takes issue with Niall Ferguson’s life of banking legend Warburg, the myths of Charles de Gaulle explored, and does Cardinal Newman deserve to be sainted?


To be thought a good man, it is always useful to cultivate a good myth. The TLS this week looks at mythmakers from the City of London to the Vatican and from General de Gaulle to Napoleon.


High Financier: The Lives and Time of Siegmund Warburg By Niall Ferguson 576 pages. The Penguin Press. $35.
Highest Finance


How good a man, for example, was the mid-20th-century London banker Sir Siegmund Warburg, the subject of Niall Ferguson’s much-praised new biography? Tim Congdon takes issue with the virtuous reputation of a man who he sees as being “lionized” by his biographer in an attempt to highlight Warburg's ethical superiority to the City slickers and shysters of today. Congdon, a longtime monetary economist and adviser to Conservative governments, is unconvinced by the noble case, judging Ferguson naïve about the low tricks that have ever been at the heart of high finance, and too keen “to see in them a public benefit that is not and never was there.” This argument may run and run.


The General: Charles De Gaulle and the France He Saved By Jonathan Fenby 720 pages. Simon & Schuster. £30.
The Myths of Charles de Gaulle


Richard Vinen is intrigued by two new books on General de Gaulle and, in particular, the light they shed on the differing reputations of Churchill and Napoleon, too. De Gaulle, he points out, had to achieve his personal mythology before he achieved any of his own victories; Napoleon needed mythmaking when his victories were long behind him. Churchill’s memoirs are treated in Britain as a source of facts and are found wanting by historians as a result; de Gaulle’s are published in France alongside Gide and Proust as “a kind of fiction” and are venerated accordingly. The books under review are Jonathan Fenby's The General and Sudhir Hazareesingh's Le Mythe Gaullien.


Newman’s Unquiet Grave: The Reluctant Saint By John Cornwell 256 pages. Continuum. £18.99.
Saint Cardinal Newman?


As British Catholics await the pope’s visit in September, during which he will beatify the influential English cardinal, John Henry Newman, there is much discussion of whether the virtues displayed by the author of Apologia Pro Vita Sua will in time boost his own mythology still further? Is a formal declaration of sainthood the imminent next step. Anthony Kenny, reviewing a biography subtitled The Reluctant Saint, praises Newman’s prose style and intellectual power, while dismissing briskly as “absurd” the notion, popularized in the media, that he was ever homosexually active. Bernard Manzo examines the paradox of Newman as the literary man who instinctively preferred reading and writing tales of dreams to becoming a part of one himself. Newman considered Scripture to be a “record of an idea that lived in its fullness in the minds of the Apostles.” The letters of St. Paul were “literature in a real and true sense,” comparable in the cardinal’s mind to great Greek plays and the most powerful political speeches.


Plus: Check out Book Beast, for more news on hot titles and authors and excerpts from the latest books.


Peter Stothard's latest book is On the Spartacus Road: A Spectacular Journey Through Ancient Italy. He is also the author of Thirty Days, a Downing Street diary of his time with British Prime Minister Tony Blair during the Iraq war.


Get a head start with the Morning Scoop email. It's your Cheat Sheet with must reads from across the Web. Get it. For more books coverage follow Book Beast on Twitter.


For inquiries, please contact The Daily Beast at editorial@thedailybeast.com.


One pill makes you larger and one pill makes you small. /

And the one that mother give you, don't do anything at all.
~ Jefferson Airplane


I was talking to a person in the medical profession who said, "some patients are looking for a magic pill that will solve all their problems."


I said welcome to my business. The same analogy holds true in personal finance. People want one simple idea that will make them rich -- preferably while they are lying on the couch watching television.


I've tried losing weight while lying on the couch, munching on potato chips. I can tell you that it doesn't work.


If you read The Millionaire Next Door or any book that studies how people become financially independent, they all basically say the same thing. Spend less than you make. Don't get into needless debt. Make a budget. Have a long term goal and be prepared to take years to get there.


The same thing holds true in living a healthy life. Eat less than you burn up. Count your calories or measure your progress. Plan to live to an old age and stay healthy until you get there.


The key on both health and money is focusing on the long run. There is not a "magic pill."


The reason that Wall Street collapsed is that too many companies were looking for their own "magic pill." They were focused on piling up short term profits, so they could get their multi-million dollar bonuses and didn't care about the long term.


Turns out that Wall Street had a magic pill. It was called the bailout. Thanks to their friends and lobbyists in Washington, Wall Street was able to screw up and have someone else clean up the mess.


It doesn't work that way for the rest of us. With your health, to coin an old song, "if you play around you lose your life." Same thing holds true with your money. Too many people are dying old and broke because they don't have a long term plan.


All this takes me to the "Move Your Money" movement.


I've been pushing it hard and you can read more about it at http://moveyourmoney.info/


The concept is simple. Move your money from a "too big to fail" bank and deposit it in a bank or credit union in your community.


Then get the charities you support to do the same. Then get the college you graduated from to do the same.


Then get your neighbors and your friends.


Right now, the top six "too big to fail" banks control about 70% of the wealth in America. That is WAY out of whack.


They got the "financial reform" bill watered down. The next time they get in trouble, they will just call their buddies in Washington and get another bailout. Unless we dilute their strength.


If more of our money is in local banks and credit unions, the Wall Street banks won't have the same power in Washington. They might not get another bailout. Better yet, Congress might get the backbone to actually regulate Wall Street so that they don't really need a bailout again.


I wasn't for the first bailout. I'm certainly not going to be for another one. Like all good things in life, Move Your Money is not a "magic pill." But it may be the start of getting us to a healthy future.


Don McNay, CLU, ChFC, MSFS, CSSC of Richmond Kentucky is an award-winning financial columnist and Huffington Post Contributor.


You can read more about Don at www.donmcnay.com


McNay founded McNay Settlement Group, a structured settlement and financial consulting firm, in 1983, and Kentucky Guardianship Administrators LLC in 2000. You can read more about both at www.mcnay.com


McNay has Master's Degrees from Vanderbilt and the American College and is in the Hall of Distinguished Alumni of Eastern Kentucky University.


McNay has written two books. Most recent is Son of a Son of a Gambler: Winners, Losers and What to Do When You Win The Lottery


McNay is a lifetime member of the Million Dollar Round Table and has four professional designations in the financial services field.


buy a penis extender

Wednesday&#39;s <b>news</b>: A night on the town with the Preds - do it for <b>...</b>

we've got a great way for Preds fans to save some money while helping local schools, reports from the World Hockey Summit, and what is surely the worst selection in Puck Daddy's "Mt. Puckmore" series so far.

I-O Data new external USB HDD will also let you backup your <b>...</b>

To pursue its growth Akihabara News is seeking for several more editors via an intership program for 6 to 9 months. Please send us a mail @ jobs@akihabaranews.com. Message. We are moving away from Feedburner, please update your RSS ...

<b>News</b> Chopper Catches Paris Hilton in Her Towel | TMZ.com

With a live KTLA news chopper hovering over her home after a man allegedly tried to break inside, Paris Hilton decided to step out on to her balcony -- in…


Friday, August 6, 2010

personal finance


Add Barriers to Your Savings Account to Protect Yourself from Impulsive Spending


There's nothing wrong with dipping into your savings account when you need to, but if you're prone to doing it a bit too often, using certain kinds of accounts can help deter you from going to them more than necessary.

Photo by Jeff Belmonte.


You can never understate the importance of budgeting, but it can be difficult when you have just one giant pile of money stashed away in a savings account. Personal finance blog Wise Bread recommends a few different types of accounts to deter you:


For short-term, emergency-fund type savings, I recommend a high-yield online savings account. It should be one that's not directly attached to your checking account, a debit card, or an ATM. That way you can't get to the money easily.


And because transfers to and from online savings accounts typically take a few days, you'll be less likely to reach into those funds for a splurge. I've found that the three to five day window really helps me to stay away from those funds. Yet, the savings account is still flexible enough to help you if you lost your job, or had a medical emergency that would require the use of the funds.


Using a high-yield savings account is good for short-term savings, since it merely makes it more difficult to get your money. For longer-term savings, however, they recommend more aggressive barriers, like a retirement account that deducts tax savings if you draw from it before retiring. These barriers may not be necessary for everyone, but if you find that impulsiveness is more a danger to your savings than anything else, it's a good way to keep yourself on track. Hit the link to read more, and share your strategies in the comments.


J.D.’s equation is correct, but it’s only part of the story. cash flow is in fact income minus expenses like the article states. However, cash flow does not correlate directly to wealth. You would naively think that wealth is the integral of cash flow with respect to time. It isn’t.


Suppose you earn $50,000. You immediately spend this money on building supplies and build a house with it. Your net cash flow is $0, but you now have a house that’s worth more than what you paid for it. You’ve got a property with a value of, say, $60,000. This is investment. Certainly you needed some cash flow to start the investing process, but cash flow itself is not wealth. Also, you now have the ability to generate $60,000 new dollars in positive cash flow by selling the house you built, in which case you can invest in something new.


The average American household income is about $3,000/month, after taxes. If you spend *all* of that on living expenses, you will never save your $50,000 to build your house. If you manage to cut your living expenses by half, you can now save your $50k in about three years. However, if instead you were able to double your income, you could save your $50k in half that time. If you take this even further and double your income again (to $12k/month) you could save you $50k in only 6 months. However, if instead you cut your living expenses by half a second time (to $750/month) it would still take you 22 months to save $50k.


You quickly hit a point of diminishing returns with cutting expenses, where each additional percent cut from your budget buys you less and less. The opposite is true for increasing your income. There is absolutely no way to save $50k in less than 16 months on $3,000/month. However, if you’re making enough money, there’s no limit to how fast you can do it.


Here’s one more example that’s not so extreme:


Set a goal to save $250,000. Pretend you want to buy a house in cash.

Start off with the same $3,000/month salary.

Start with the same $3,000/month living expenses.


Scenario 1: Your living expenses never change, but each year, you manage to increase your income 7% over the previous year. This seems feasible, it’s not a “get rich quick” scheme, you can probably find some way to improve your performance in whatever business you’re in by about this much.


You save your $250,000 in a bit over 12 years. At the end of the 12 years, you make about $120k/year. This is definitely a good salary, but it’s not ridiculously, infeasibly high.


Scenario 2:

You keep the same salary every year, but cut your expenses by 7%.


You save your $250k in 17 years, which is significantly longer. You’re also living on $920/month at the end of this, which is probably infeasible in real life. You just can’t keep cutting and cutting and cutting to this degree.


Scenario 3:

You combine both 1 and 2, both increasing your income by 7% every year, and cutting expenses the same amount. You’d think this would make a huge difference, right?


You’ll save your $250k in 10 years. This is definitely an improvement over either one of the other scenarios, but it’s not nearly the same sort of improvement you see if you solely increase income instead of solely decreasing spending. It also requires you to live on $1500/month at the end, which is certainly a lot more feasible that $920, but you still may think that’s a bit low.


This whole calculation ignores inflation (meaning, your 7% raise per year is probably more like 10% in absolute terms). It also means that at the end, when I say you’re living on $920/month, that’s $920 dollars at 2010 value, not 2027 value.


This is essentially the same concept that J.D. likes to call ‘the power of compound interest’, except applied in a slightly different way.


One other note on this example: selling your ’stuff’ makes almost no difference here. Even assuming you had $10k worth of stuff to get rid of at the beginning of this, it only buys you a few extra months in any of these scenarios. This is because a single, one-time influx of $10k is small in a scenario that takes 10-17 years to play out. At the end of these scenarios, you’re saving in the ballpark of $2000-$5000 every month. The extra $10k just isn’t that big of a deal any more. Selling ’stuff’ can help you reduce debts and stop paying interest to other parties if you can do it all at once, but it really doesn’t help you build long-term savings very well.


I know the site is called “get rich slowly”, but I like to think that is meant to convey an idea of perseverance and the fact that “get rick quick” schemes don’t work. It’s not meant to imply you should go artificially slower than you have to, just because.


In short: ask for a raise every year, even if you don’t always get it. Don’t be afraid to take a job at a competing company if they’ll offer you a better salary (assuming the job is otherwise similar). You don’t need to start your own company to make a few more percent every year. Just be valuable in your industry, show that to your employers, and don’t be afraid to ask for raises.


penis extender

Virtual Economics Winner during Teaching Personal Finance Workshop at WRLC 2008 Conference by Council for Economic Education


Add Barriers to Your Savings Account to Protect Yourself from Impulsive Spending


There's nothing wrong with dipping into your savings account when you need to, but if you're prone to doing it a bit too often, using certain kinds of accounts can help deter you from going to them more than necessary.

Photo by Jeff Belmonte.


You can never understate the importance of budgeting, but it can be difficult when you have just one giant pile of money stashed away in a savings account. Personal finance blog Wise Bread recommends a few different types of accounts to deter you:


For short-term, emergency-fund type savings, I recommend a high-yield online savings account. It should be one that's not directly attached to your checking account, a debit card, or an ATM. That way you can't get to the money easily.


And because transfers to and from online savings accounts typically take a few days, you'll be less likely to reach into those funds for a splurge. I've found that the three to five day window really helps me to stay away from those funds. Yet, the savings account is still flexible enough to help you if you lost your job, or had a medical emergency that would require the use of the funds.


Using a high-yield savings account is good for short-term savings, since it merely makes it more difficult to get your money. For longer-term savings, however, they recommend more aggressive barriers, like a retirement account that deducts tax savings if you draw from it before retiring. These barriers may not be necessary for everyone, but if you find that impulsiveness is more a danger to your savings than anything else, it's a good way to keep yourself on track. Hit the link to read more, and share your strategies in the comments.


J.D.’s equation is correct, but it’s only part of the story. cash flow is in fact income minus expenses like the article states. However, cash flow does not correlate directly to wealth. You would naively think that wealth is the integral of cash flow with respect to time. It isn’t.


Suppose you earn $50,000. You immediately spend this money on building supplies and build a house with it. Your net cash flow is $0, but you now have a house that’s worth more than what you paid for it. You’ve got a property with a value of, say, $60,000. This is investment. Certainly you needed some cash flow to start the investing process, but cash flow itself is not wealth. Also, you now have the ability to generate $60,000 new dollars in positive cash flow by selling the house you built, in which case you can invest in something new.


The average American household income is about $3,000/month, after taxes. If you spend *all* of that on living expenses, you will never save your $50,000 to build your house. If you manage to cut your living expenses by half, you can now save your $50k in about three years. However, if instead you were able to double your income, you could save your $50k in half that time. If you take this even further and double your income again (to $12k/month) you could save you $50k in only 6 months. However, if instead you cut your living expenses by half a second time (to $750/month) it would still take you 22 months to save $50k.


You quickly hit a point of diminishing returns with cutting expenses, where each additional percent cut from your budget buys you less and less. The opposite is true for increasing your income. There is absolutely no way to save $50k in less than 16 months on $3,000/month. However, if you’re making enough money, there’s no limit to how fast you can do it.


Here’s one more example that’s not so extreme:


Set a goal to save $250,000. Pretend you want to buy a house in cash.

Start off with the same $3,000/month salary.

Start with the same $3,000/month living expenses.


Scenario 1: Your living expenses never change, but each year, you manage to increase your income 7% over the previous year. This seems feasible, it’s not a “get rich quick” scheme, you can probably find some way to improve your performance in whatever business you’re in by about this much.


You save your $250,000 in a bit over 12 years. At the end of the 12 years, you make about $120k/year. This is definitely a good salary, but it’s not ridiculously, infeasibly high.


Scenario 2:

You keep the same salary every year, but cut your expenses by 7%.


You save your $250k in 17 years, which is significantly longer. You’re also living on $920/month at the end of this, which is probably infeasible in real life. You just can’t keep cutting and cutting and cutting to this degree.


Scenario 3:

You combine both 1 and 2, both increasing your income by 7% every year, and cutting expenses the same amount. You’d think this would make a huge difference, right?


You’ll save your $250k in 10 years. This is definitely an improvement over either one of the other scenarios, but it’s not nearly the same sort of improvement you see if you solely increase income instead of solely decreasing spending. It also requires you to live on $1500/month at the end, which is certainly a lot more feasible that $920, but you still may think that’s a bit low.


This whole calculation ignores inflation (meaning, your 7% raise per year is probably more like 10% in absolute terms). It also means that at the end, when I say you’re living on $920/month, that’s $920 dollars at 2010 value, not 2027 value.


This is essentially the same concept that J.D. likes to call ‘the power of compound interest’, except applied in a slightly different way.


One other note on this example: selling your ’stuff’ makes almost no difference here. Even assuming you had $10k worth of stuff to get rid of at the beginning of this, it only buys you a few extra months in any of these scenarios. This is because a single, one-time influx of $10k is small in a scenario that takes 10-17 years to play out. At the end of these scenarios, you’re saving in the ballpark of $2000-$5000 every month. The extra $10k just isn’t that big of a deal any more. Selling ’stuff’ can help you reduce debts and stop paying interest to other parties if you can do it all at once, but it really doesn’t help you build long-term savings very well.


I know the site is called “get rich slowly”, but I like to think that is meant to convey an idea of perseverance and the fact that “get rick quick” schemes don’t work. It’s not meant to imply you should go artificially slower than you have to, just because.


In short: ask for a raise every year, even if you don’t always get it. Don’t be afraid to take a job at a competing company if they’ll offer you a better salary (assuming the job is otherwise similar). You don’t need to start your own company to make a few more percent every year. Just be valuable in your industry, show that to your employers, and don’t be afraid to ask for raises.


online stock trading online stock trading how to lose weight fast

NFL Training Camp <b>News</b>: MRI Shows No Damage To Albert <b>...</b>

NFL Training Camp News: MRI Shows No Damage To Albert Haynesworth's Knee.

Next OpFlash &quot;takes on board feedback&quot; <b>News</b> - Page 1 | Eurogamer.net

Read our news of Next OpFlash. ... Latest News. Next Operation Flashpoint named . Latest Screenshots. Screenshot Today 09:40 . Developer EA DICE. Publisher Electronic Arts. Release Date TBC ...

Johann Hari: And the Most Inspiring Good <b>News</b> Story of the Year Is...

After slavery was abolished in 1833, Britain's GDP fell by 10 percent -- but they knew that cheap goods and fat profits made from flogging people until they broke were not worth having. Do we?


Virtual Economics Winner during Teaching Personal Finance Workshop at WRLC 2008 Conference by Council for Economic Education


big white booty


Thursday, August 5, 2010

managing personal finances


In 2006, recent Harvard grad Alexa von Tobel was headed for a job at Morgan Stanley. But though she would soon be managing the bank’s investments, she realized she didn’t know the first thing about her own finances. Most financial guides seemed to be written for middle-aged readers with millions in assets, rather than recent college grads. "I was reading every book I could find, but none of them spoke to me," she says. So she came up with the idea for LearnVest, an online personal-finance resource for young women like her, and ended up writing an 80-page business plan.


After two years at Morgan Stanley, von Tobel entered Harvard Business School in 2008. But upon winning a business plan competition held by Astia, a non-profit that supports women entrepreneurs, she took a five-year leave of absence and invested $75,000 of her Wall Street earnings to start LearnVest in November. She quickly enlisted advisors, including Betsy Morgan, the former CEO of the Huffington Post, and Catherine Levene, the former COO of DailyCandy, to help develop the site’s content and technology. In January 2009, she secured $1.1 million in seed funding from executives at Goldman Sachs.


LearnVest’s site launched a year later and has since signed up more than 100,000 members. It offers online budgeting calculators, video chats with certified financial planners on the company’s staff, and free e-mail tutorials on topics such as opening an IRA. The company earns revenue from advertising and by referring its users to companies such as TD Ameritrade. In April, after just four weeks of fundraising, von Tobel closed a $4.5 million investment round led by Accel Partners, which has also invested in Facebook and Etsy. (Incidentally, Facebook CEO Mark Zuckerberg lived in the same dorm as von Tobel at Harvard.)


Von Tobel likens LearnVest to an online version of The Suze Orman Show, but with the goal of reinforcing positive finance habits early on. “Suze Orman helps 45-year-old women get out of debt,” she says. “Why not reach 20-year-olds to keep them from getting into debt?”


As you’ll read tomorrow (or Monday), I’ve entered a new phase in my life. After years of hard work and long hours building this blog (time that I’ve enjoyed), I’ve been shifting things around so that I have more free time. As a result, I’m going to have more time to devote to creating quality blog posts, instead of rushing around at the last minute looking for something to write about.


Because of this, it’s time yet again to take requests. I do this about once a year, and it’s a great way to get a feel for what GRS readers are interested in. I’d be grateful if you’d take the time to leave a comment below with topic suggestions or article requests. It doesn’t matter if we’ve covered the subject in the past. If you’d like me (or one of the other GRS staff) to write about it, let me know.


Have there been too many articles about credit cards? Too few articles about credit cards? Would you like to know more about individual savings accounts? Do you like the articles about the psychology of spending? Would it be helpful to have somebody come in to explain insurance concepts in plain English? Should I try to persuade my wife to share more of her recipes now and then? Let me know what you’d like to read about!


While you’re all providing feedback about the site, here are a few recent articles of note:


Over at The Simple Dollar, Trent and his readers had a thoughtful discussion about the obligations of wealth. “I think there is some inherent distrust of the rich in the mainstream of American society,” Trent writes as he describes how a wealthy person can keep from alienating his friends. There’s so much to say about this topic; I’m tempted to write an entire article about it.


GRS reader Steven writes a blog called Hundred Goals, which is about achieving your goals while managing your finances. After Sierra’s post this morning about travel, he dropped me a line to let me know that he has a recent article about how to have a great vacation.


Speaking of vacation, my pal Jason over at No Credit Needed spent time compiling day-use fees and free days for state parks across the United States. Handy page to bookmark!


And here’s more travel! At The Art of Non-Conformity, my good friend Chris Guillebeau has posted a beginner’s guide to travel hacking. I’ve been asking him to share this info for a long time; now I’ve got to take responsibility to use the knowledge he’s shared.


Finally, I’ve been giving a lot of interviews lately. I’m much more comfortable with these than I used to be. (They used to scare me to death!) Some examples:


  • Colleen from The Frisky interviewed me about how to save money even when you’re living paycheck to paycheck. This is a tough quandary, something I’m asked about a lot.


  • In an interview with BeFrugal, I discuss frugality, happiness, and conscious spending. (Note: “the ballot” should be “the balance” — I must have mumbled.)


  • Jeff Rose at Good Financial Cents also interviewed me. This interview is very much about the process of writing a book, which may or may not interest you.


  • I also spoke with Beverly Harzog from Card Ratings. We chatted about credit cards, of course, but also about other aspects of personal finance.


  • Finally, USA Weekend has a short piece on how to give your 401(k) a midyear check, for which author Richard Eisenberg interviewed me back in May. This is a perfect example of how much work goes into even a small newspaper article. Eisenberg spent 20-30 minutes on the phone with me, and I’m sure he did the same with the other folks he quotes. Plus, I’ll bet he spent a lot of time writing. I wouldn’t be surprised if there were 4-6 hours in this small piece.


Okay, one last thing before I go. Tim pointed me to a two-year-old New York Times series about the debt trap, which includes an interactive infographic showing average household debt loads over the past century.


That’s enough links for today. Please do leave a comment with topic requests or other feedback. Meanwhile, it’s time for me to go do some yardwork…


penis extender

MABUHAY ALLIANCE HOST THE 6TH ANNUAL ECONOMIC DEVELOPMENT CONFERENCE by mabuhayalliance


Friday, July 30, 2010

managing your personal finances


penis enlargement

2010 Midterms: Latest <b>News</b> on the Hot Races

2010 Midterms: Latest News on the Hot Races. 11 hours ago. 0 Comments Say Something ». Print Text Size. Bruce Drake. Contributing Editor. Author Bio » � Contact Author » � Subscribe : California Power of Environmental Issues a Wild Card ...

Northwest <b>News</b>: King County judge won&#39;t take 3rd baby away from <b>...</b>

Two cases, two sets of parents, two sets of charges.

&#39;Idol&#39; <b>News</b> - The Ellen DeGeneres Show

Ellen, I have to say I was surprised by this news, as I LOVED watching you with the kids on Idol. You will definitely be missed on the show. I respect your decision, however, and only want happiness for you. You have made me laugh, ...


Quicken Home &amp; Business 2008: Manage both your personal and business finances together in one place by Quicken Online


internet marketing course

2010 Midterms: Latest <b>News</b> on the Hot Races

2010 Midterms: Latest News on the Hot Races. 11 hours ago. 0 Comments Say Something ». Print Text Size. Bruce Drake. Contributing Editor. Author Bio » � Contact Author » � Subscribe : California Power of Environmental Issues a Wild Card ...

Northwest <b>News</b>: King County judge won&#39;t take 3rd baby away from <b>...</b>

Two cases, two sets of parents, two sets of charges.

&#39;Idol&#39; <b>News</b> - The Ellen DeGeneres Show

Ellen, I have to say I was surprised by this news, as I LOVED watching you with the kids on Idol. You will definitely be missed on the show. I respect your decision, however, and only want happiness for you. You have made me laugh, ...


big white booty

Quicken Home &amp; Business 2008: Manage both your personal and business finances together in one place by Quicken Online


Thursday, July 22, 2010

manage personal finances


Five Best Personal Money Management Sites


Web-based financial management tools have grown in sophistication to the point where many people manage their entire financial lives with online tools. Here's a look at five of the most popular personal money management sites.

Photo a mashup of images by Leonardini and Wilton.


Earlier this week we asked you to share your favorite personal money management site; now we're back to highlight the five most popular contenders.


Click on the screenshots below to take a closer look.


Buxfer (Basic: Free, Premium: From $2.79/month)


Many people are hesitant to use online banking services because of security concerns. Buxfer's compromise to provide ease of use while also assuring users and keeping things as controlled as they would like is to offer multiple methods for storing your credentials. You can manually synchronize your financial accounts with the site, you can store your passwords and login credentials locally using Google Gears, Firefox, or Safari, or you can use the Firebux Firefox extension—Firebux helps you automate the process of downloading financial data from your banking institutions and reviewing Buxfer data. If you'd like to skip the hassle of handling your own syncing, Buxfer offers automatic nightly syncing of your financial data, automatically logging into and pulling data from your various online money portals. Buxfer comes in three flavors: Basic (free), Plus ($2.79 per month), and Pro ($3.79 per month). All accounts include features like split bills, automatic tagging, and mobile access, but you'll pay a premium for unlimited budgets, bill reminders, and balance projections. You can try a live demo of Buxfer here.


Yodlee MoneyCenter (Free)


As many readers were quick to point out, Yodlee provides the guts to the user sites for hundreds of banking and financial services. Organizations like Mint, Thrive, and large banks like Chase use rebranded but Yodlee-powered interfaces. Yodlee users will often characterize Yodlee as similar to Mint, but without such a strong emphasis on flashy graphics. Instead it focuses more on analyzing your raw data—transaction descriptions, for example, are easier to search and more detailed. Yodlee can import data from thousands of institutions, help you generate a budget, automate your bill paying, and send out user-defined alerts. If you like the idea of a site like Mint but want more fine-grained control and the ability to manually tweak things when necessary, Yodlee is a solid alternative.


Mint (Free)


Mint has risen to prominence as a major player among web-based financial management tools by putting an extreme emphasis on user-friendliness and automation. The focus on automation is so strong, in fact, they only recently added the ability to add in any sort of manual transactions. By providing Mint with your various logins, you can track all your financial accounts in one place—checking, savings, credit cards, investments—and easily generate budgets and projections based off your data. Mint has won many people over, especially in the younger demographic, by being the first tool they've used to really get a good look at their money and where it's going.


ClearCheckbook (Basic: Free, Premium: $4/month)


ClearCheckbook is a web-based checking account ledger on steroids. You can track your spending, input your daily expenses from the web-interface or from your iPhone, Android, or Palm, and generate a budget with spending limits. Upgrading to a premium account gets you a custom report tool, custom transaction fields, future balance projection, and editing of the auto-suggest feature. Visit ClearCheckbook at the link above to check out the video tours of both the free and premium accounts—available at the bottom of the main page.


Mvelopes ($39.60/quarter)


Mvelopes is a robust web-based financial tool built on the old principle of budgeting with envelopes—each budget category gets an envelope with a set amount of money. Its focus on an old budgeting technique, however, doesn't mean you're stuck with dated tools. Mvelopes automatically pulls transaction data from hundreds of financial institutions, supports automatic bill payment, and helps you generate snapshots of your net worth as you adjust your budget and goals. Mvelopes is notable for being the only contender in the Hive without a free account option, a testament perhaps to how happy people are with the service that it made an appearance in the top five despite the lack of free-as-in-beer option.


Now that you've had a chance to look over the top five contenders for best personal money management sites, it's time to cast a vote for your favorite:


Have a favorite web-based tool that didn't get a nod or want to talk up your favorite a bit more? Let's hear it in the comments. Have an idea for the next Hive Five? Send us an email at tips@lifehacker.com with "Hive Five" in the subject line and we'll do our best to get your idea the attention it deserves.


Send an email to Jason Fitzpatrick, the author of this post, at jason@lifehacker.com.


Web technology has revolutionized finance by making it easier than ever to monitor cash flow and track trends in your spending. Mint.com has been a leader in this realm for personal finance: its technology helps you track multiple accounts, analyze spending trends, and manage financial goals.

There isn’t a clear counterpart to class='blippr-nobr'>Mintclass="blippr-nobr">Mint for businesses, though. That’s where inDinero, a Y-Combinator-funded startup, comes in.

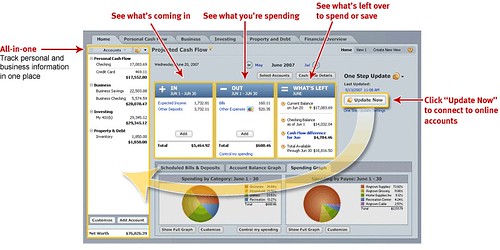
inDinero, which launches today, is a web-based financial dashboard for small businesses. Like Mint, it aggregates financial data from bank accounts, investments, and other sources and places them in a simple, easy-to-navigate interface where you can quickly see your income, spending, recent activity, and your financial runway.

The app is divided into five parts: Dashboard, Income, Spending, Planning and Trends. Dashboard provides an overview of your business finances, Income provides detailed information about your income streams, Spending breaks down your different costs, Planning helps you set goals for your business, and Trends analyzes and graphs out spending and income trends in order to provide useful insights.

Businesses need this type of information in order to minimize costs while maximizing revenues. While solutions such as Mint also aggregate financial information and analyze it, they are not focused on small businesses. We look forward to seeing inDinero’s business toolset grow and evolve.

Image courtesy of iStockphotoclass="blippr-nobr">iStockphoto, jwohlfeil

For more Business coverage:

    class="f-el">class="cov-twit">Follow Mashable Businessclass="s-el">class="cov-rss">Subscribe to the Business channelclass="f-el">class="cov-fb">Become a Fan on Facebookclass="s-el">class="cov-apple">Download our free apps for iPhone and iPad

penis enlargement

Navigate The 3D Globe of <b>News</b>

TV network ABC has released a custom ABC News iPad app that's interesting for two reasons—its clever use of HTML5 and the amazing rotating Globe of News.

More Touchscreen Innovation: ABC <b>News</b> for iPad Launches

Launched this week, ABC News for iPad is a notable free application which continues the trend of companies developing innovative and creative interfaces designed specifically for tablet-sized touch ...

ASUS EP101TC Now Shipping with Android | Netbooknews - Netbooks <b>...</b>

Today the Netbook News team went down to the ASUS headquarters to hang out with the Eee Pad team, and we learned something that actually made us breath a sigh of relief. The EP101TC pad will dropping Windows CE and will be shipped with ...


MABUHAY ALLIANCE HOST THE 6TH ANNUAL ECONOMIC DEVELOPMENT CONFERENCE by mabuhayalliance


internet marketing course

Navigate The 3D Globe of <b>News</b>

TV network ABC has released a custom ABC News iPad app that's interesting for two reasons—its clever use of HTML5 and the amazing rotating Globe of News.

More Touchscreen Innovation: ABC <b>News</b> for iPad Launches

Launched this week, ABC News for iPad is a notable free application which continues the trend of companies developing innovative and creative interfaces designed specifically for tablet-sized touch ...

ASUS EP101TC Now Shipping with Android | Netbooknews - Netbooks <b>...</b>

Today the Netbook News team went down to the ASUS headquarters to hang out with the Eee Pad team, and we learned something that actually made us breath a sigh of relief. The EP101TC pad will dropping Windows CE and will be shipped with ...


big white booty

MABUHAY ALLIANCE HOST THE 6TH ANNUAL ECONOMIC DEVELOPMENT CONFERENCE by mabuhayalliance


Wednesday, July 21, 2010

how to manage personal finances


online stock trading

CampusProgress.org | <b>news</b> | Immigration <b>News</b> Coming Out of Arizona

In other news, more than 500 National Guard soldiers will be coming to the border in the next few months. Altogether, 1200 soldiers will be deployed to the border. At the announcement earlier this week, an official with the Immigration ...

ASUS EP101TC Now Shipping with Android | Netbooknews - Netbooks <b>...</b>

Today the Netbook News team went down to the ASUS headquarters to hang out with the Eee Pad team, and we learned something that actually made us breath a sigh of relief. The EP101TC pad will dropping Windows CE and will be shipped with ...

Liberal journalists suggest government shut down Fox <b>News</b> | The <b>...</b>

FILE - In this Jan. 22, 2009 file photo, President Barack Obama, center, stands near Fox News' Major Garrett, left, in the kitchen of the Brady press briefing room at the White House in Washington. (AP Photo/Manuel Balce Ceneta) ...


MABUHAY ALLIANCE HOST THE 6TH ANNUAL ECONOMIC DEVELOPMENT CONFERENCE by mabuhayalliance


Tuesday, July 20, 2010

managing your personal finances

As you’ll read tomorrow (or Monday), I’ve entered a new phase in my life. After years of hard work and long hours building this blog (time that I’ve enjoyed), I’ve been shifting things around so that I have more free time. As a result, I’m going to have more time to devote to creating quality blog posts, instead of rushing around at the last minute looking for something to write about.


Because of this, it’s time yet again to take requests. I do this about once a year, and it’s a great way to get a feel for what GRS readers are interested in. I’d be grateful if you’d take the time to leave a comment below with topic suggestions or article requests. It doesn’t matter if we’ve covered the subject in the past. If you’d like me (or one of the other GRS staff) to write about it, let me know.


Have there been too many articles about credit cards? Too few articles about credit cards? Would you like to know more about individual savings accounts? Do you like the articles about the psychology of spending? Would it be helpful to have somebody come in to explain insurance concepts in plain English? Should I try to persuade my wife to share more of her recipes now and then? Let me know what you’d like to read about!


While you’re all providing feedback about the site, here are a few recent articles of note:


Over at The Simple Dollar, Trent and his readers had a thoughtful discussion about the obligations of wealth. “I think there is some inherent distrust of the rich in the mainstream of American society,” Trent writes as he describes how a wealthy person can keep from alienating his friends. There’s so much to say about this topic; I’m tempted to write an entire article about it.


GRS reader Steven writes a blog called Hundred Goals, which is about achieving your goals while managing your finances. After Sierra’s post this morning about travel, he dropped me a line to let me know that he has a recent article about how to have a great vacation.


Speaking of vacation, my pal Jason over at No Credit Needed spent time compiling day-use fees and free days for state parks across the United States. Handy page to bookmark!


And here’s more travel! At The Art of Non-Conformity, my good friend Chris Guillebeau has posted a beginner’s guide to travel hacking. I’ve been asking him to share this info for a long time; now I’ve got to take responsibility to use the knowledge he’s shared.


Finally, I’ve been giving a lot of interviews lately. I’m much more comfortable with these than I used to be. (They used to scare me to death!) Some examples:


  • Colleen from The Frisky interviewed me about how to save money even when you’re living paycheck to paycheck. This is a tough quandary, something I’m asked about a lot.


  • In an interview with BeFrugal, I discuss frugality, happiness, and conscious spending. (Note: “the ballot” should be “the balance” — I must have mumbled.)


  • Jeff Rose at Good Financial Cents also interviewed me. This interview is very much about the process of writing a book, which may or may not interest you.


  • I also spoke with Beverly Harzog from Card Ratings. We chatted about credit cards, of course, but also about other aspects of personal finance.


  • Finally, USA Weekend has a short piece on how to give your 401(k) a midyear check, for which author Richard Eisenberg interviewed me back in May. This is a perfect example of how much work goes into even a small newspaper article. Eisenberg spent 20-30 minutes on the phone with me, and I’m sure he did the same with the other folks he quotes. Plus, I’ll bet he spent a lot of time writing. I wouldn’t be surprised if there were 4-6 hours in this small piece.


Okay, one last thing before I go. Tim pointed me to a two-year-old New York Times series about the debt trap, which includes an interactive infographic showing average household debt loads over the past century.


That’s enough links for today. Please do leave a comment with topic requests or other feedback. Meanwhile, it’s time for me to go do some yardwork…


As you’ll read tomorrow (or Monday), I’ve entered a new phase in my life. After years of hard work and long hours building this blog (time that I’ve enjoyed), I’ve been shifting things around so that I have more free time. As a result, I’m going to have more time to devote to creating quality blog posts, instead of rushing around at the last minute looking for something to write about.


Because of this, it’s time yet again to take requests. I do this about once a year, and it’s a great way to get a feel for what GRS readers are interested in. I’d be grateful if you’d take the time to leave a comment below with topic suggestions or article requests. It doesn’t matter if we’ve covered the subject in the past. If you’d like me (or one of the other GRS staff) to write about it, let me know.


Have there been too many articles about credit cards? Too few articles about credit cards? Would you like to know more about individual savings accounts? Do you like the articles about the psychology of spending? Would it be helpful to have somebody come in to explain insurance concepts in plain English? Should I try to persuade my wife to share more of her recipes now and then? Let me know what you’d like to read about!


While you’re all providing feedback about the site, here are a few recent articles of note:


Over at The Simple Dollar, Trent and his readers had a thoughtful discussion about the obligations of wealth. “I think there is some inherent distrust of the rich in the mainstream of American society,” Trent writes as he describes how a wealthy person can keep from alienating his friends. There’s so much to say about this topic; I’m tempted to write an entire article about it.


GRS reader Steven writes a blog called Hundred Goals, which is about achieving your goals while managing your finances. After Sierra’s post this morning about travel, he dropped me a line to let me know that he has a recent article about how to have a great vacation.


Speaking of vacation, my pal Jason over at No Credit Needed spent time compiling day-use fees and free days for state parks across the United States. Handy page to bookmark!


And here’s more travel! At The Art of Non-Conformity, my good friend Chris Guillebeau has posted a beginner’s guide to travel hacking. I’ve been asking him to share this info for a long time; now I’ve got to take responsibility to use the knowledge he’s shared.


Finally, I’ve been giving a lot of interviews lately. I’m much more comfortable with these than I used to be. (They used to scare me to death!) Some examples:


  • Colleen from The Frisky interviewed me about how to save money even when you’re living paycheck to paycheck. This is a tough quandary, something I’m asked about a lot.


  • In an interview with BeFrugal, I discuss frugality, happiness, and conscious spending. (Note: “the ballot” should be “the balance” — I must have mumbled.)


  • Jeff Rose at Good Financial Cents also interviewed me. This interview is very much about the process of writing a book, which may or may not interest you.


  • I also spoke with Beverly Harzog from Card Ratings. We chatted about credit cards, of course, but also about other aspects of personal finance.


  • Finally, USA Weekend has a short piece on how to give your 401(k) a midyear check, for which author Richard Eisenberg interviewed me back in May. This is a perfect example of how much work goes into even a small newspaper article. Eisenberg spent 20-30 minutes on the phone with me, and I’m sure he did the same with the other folks he quotes. Plus, I’ll bet he spent a lot of time writing. I wouldn’t be surprised if there were 4-6 hours in this small piece.


Okay, one last thing before I go. Tim pointed me to a two-year-old New York Times series about the debt trap, which includes an interactive infographic showing average household debt loads over the past century.


That’s enough links for today. Please do leave a comment with topic requests or other feedback. Meanwhile, it’s time for me to go do some yardwork…


internet marketing course

You need not hire a money coach to manage your personal finances. The steps to having an organized budget while being debt-free is actually very simple. Discipline is the principal thing that one needs in order to achieve a money-worry-free life.

You have probably already heard of what you are about to read here but it will do you good to hear it again. A friend or family member may actually have told you these a thousand times- you were just too stubborn then to listen to some good advice. It will probably help, however, that you get this advice from a stranger and you will come to see that these are generic rules and that your friends and family are not just being biased.

Number 1: Live within your means. Fine dining every night is for Oprah and Donald Trump. Unless you make almost the same amount, you can't afford to do so. Restos sell their food at almost 75% more than the cost of the food. That is because you also pay for the ambience, the comfort and service. You may not have all these at home, but you'd be a lot comfortable knowing that you don't owe those credit card companies anything just for the same meal you could have eaten at home.

Number 2: Buy what you only NEED, not what you WANT. No, those cargo pants are not an investment. No, you won't be using that Thanks-for keeping-a-secret-roomie greeting card. No, a $20 bra is not essential to your confidence.

The costs of these things are usually the ones that pile up. You'd be wondering where your paycheck went when it's every week that you buy those cute paperweights or some other impulse item. Again, buy what you only need. Of course it does not mean that you don't get to treat yourself. You should do so-every once in a while, and when you know you can afford it.

Number 3: Set money aside for your bills (utility, insurance, mortgage etc.). If you do, then you will know how much you can only spend for extra stuff. You yourself know that you need fresh water and electricity more than those killer boots.

Number 4: Acquire TWO credit cards at the most. Really, how many credit cards do you need? And what for? For you to have debts in 5 companies rather than just 2? Having a minimum number of credit cards allows you to track your expenses more thoroughly. You will also have more control when you know that you can only have too much debt in one company and not distribute these into 5.

Now that you've heard the unbiased basics, everything else is up to you.


penis enlargement

Microsoft confirms Kinect price Xbox 360 <b>News</b> - Page 1 | Eurogamer.net

Read our Xbox 360 news of Microsoft confirms Kinect price.

Tropical Trouble? « FOX <b>News</b> Weather Blog

Good morning all! Just read that New York is about to have its hottest July on record, and I can.

Disgraced USDA Official Blames Fox <b>News</b> and Tea Party For Her <b>...</b>

The USDA employee that was forced to resign Monday as a result of racist comments she made at an NAACP gathering in March has blamed Fox News and the Tea Party for her inability to convince her employers of her innocence. ...


how to lose weight fast